
A reseller credit balance records the service-accounting units currently available in a supplier's panel. Credits are defined by that supplier's actual rules, rather than by a universal IPTV conversion. One credit must not be assumed to equal one month, one screen or one customer account without documented terms. A balance can increase through purchases or adjustments and decrease through supported activations, renewals or other chargeable actions. It is also different from bank cash or customer revenue. Understanding the unit and transaction rules is necessary before estimating how many activations a balance can support or what a particular sale costs.
Reseller credit balance and Cash balance
Panel credits are service-accounting units, not automatically withdrawable money.
Read the consumption rule first
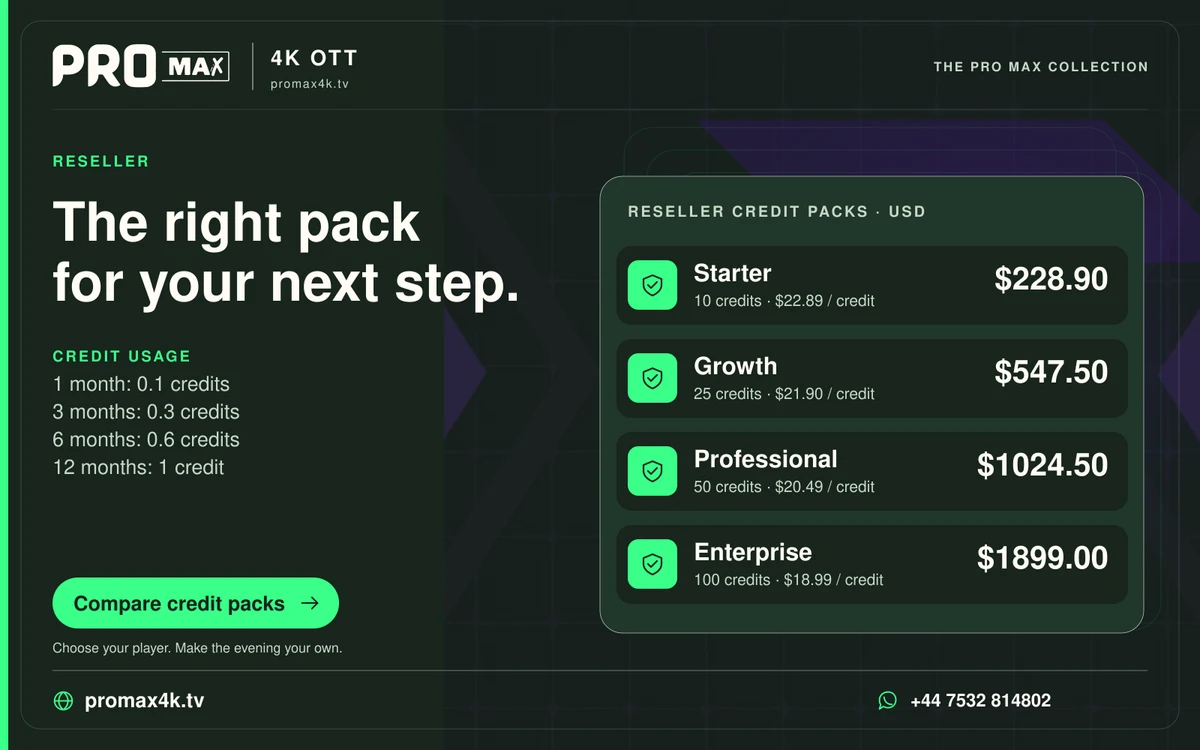
Credit usage is service-specific. Pro Max uses 0.1 credits for 1 month, 0.3 for 3 months, 0.6 for 6 months and 1 credit for 12 months. Use the selected term to calculate the expected deduction, then compare it with the actual panel transaction. Connection allowances, adjustments, transfer rights and credit expiry are separate terms.
Cash value and panel units are separate
Buying credits creates an outgoing payment and an inventory of service units under the supplier's arrangement. It does not automatically create customer sales, cash profit or a right to withdraw unused units as money. Refundability, expiration and transferability require explicit terms. Keep the purchase currency and unit quantity in the record so later cost calculations do not confuse credits with a monetary balance.
Reconcile changes with transactions
Start with an opening balance, add purchases and authorized adjustments, and subtract documented consumption to calculate the expected closing balance. Compare it with the panel after allowing for known pending operations. An unexplained difference may reflect an omitted renewal or correction rather than a platform fault. Keep transaction references and times while avoiding customer passwords in the bookkeeping record.
An illustrative example
A Starter balance of 10 credits can fund 100 one-month allocations at 0.1 credits each, or 10 twelve-month allocations at 1 credit each, before other adjustments. These are alternative uses of the same inventory. They do not establish customer demand, a resale price or a right to withdraw credits as cash.
Practical actions
- Confirm the supplier’s actual credit consumption and adjustment rules.
- Record purchased units separately from their monetary purchase cost.
- Reconcile opening balance, additions, deductions and the observed closing balance.