Reconciliation explains the difference between the opening and closing credit balance. Use recorded purchases, confirmed deductions and any documented adjustments to calculate an expected closing balance. Compare that figure with the actual panel balance for the same moment. Customer passwords are not part of this arithmetic. An order reference, allocation type and credit quantity usually provide a more useful audit trail than a screenshot containing account secrets.
Choose one time boundary
A balance comparison needs a shared cutoff. If a pack purchase appears in one record before the panel updates, two otherwise correct totals can disagree temporarily. Record when each balance was read, and separate pending work from confirmed deductions. Avoid changing old entries simply to force agreement with the latest screen. A ledger should explain what happened, including an unresolved difference, rather than conceal the difference in an unnamed adjustment.
Keep adjustments visible
An adjustment needs its own reference and explanation. Do not silently overwrite the opening balance or alter a previous customer deduction. If the service corrects an allocation, record the documented correction separately from the original action. This preserves the sequence needed to understand a later discrepancy. The panel’s actual behaviour remains the source for credit deductions; a spreadsheet should not invent a different plan-conversion rule.
Investigate the narrow difference
Compare the unexplained amount with recent allocation quantities and pack purchases. A duplicate entry, a pending action or a missing confirmed deduction may explain it. That is a useful hypothesis, not proof that a particular customer caused the discrepancy. Ask for a transaction reference through the private support route. Keep the reconciliation report limited to the identifiers needed to resolve the arithmetic.
A practical sequence
0 of 4 steps completed on this page.
An example to work through
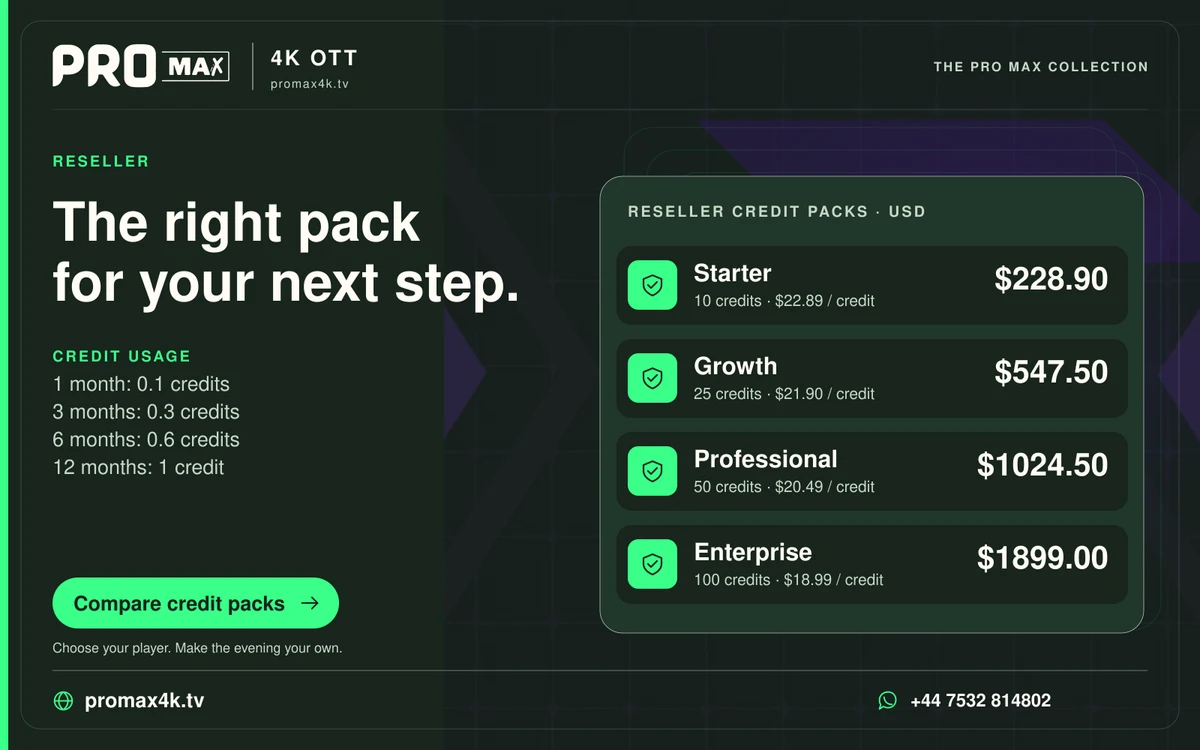
An opening balance of 100 credits plus a 25-credit Growth purchase minus 1.8 confirmed credits gives 123.2 credits. If the panel shows 122.6, investigate the 0.6-credit difference. Retain the transaction records instead of editing the expected balance to force a match.